Financial Literacy for Beginners: Essential Personal Finance Skills
You earn a solid paycheck. You cover rent, the credit card bill shows up, and by the 20th your bank account looks like a ghost town. Sound familiar? I’ve watched smart, hardworking people repeat this cycle for years, and a low salary almost never explains it. A missing skill does. Financial literacy, the know-how to earn, spend, save, borrow and invest with confidence, shapes where your money goes long before the next paycheck arrives.
The good news: you can learn it, and you can start TODAY. Rising prices, student loans, tap-to-pay apps and a thousand investing opinions on social media make money feel harder to handle than ever. This guide to financial literacy for beginners walks you through the personal finance basics in plain English: budgeting, emergency savings, credit scores, debt payoff, compound interest and your first investments. You get real numbers, simple examples and steps you can use this week.
Nobody expects you to get rich overnight, and I won’t promise that. You just need enough financial education to make smarter money management decisions, one choice at a time. Every confident money person you admire once felt as lost as you might feel right now. Your first win starts with the next section.
1. What Is Financial Literacy and Why Is It Important?
Financial literacy means you understand how money works and use that knowledge to make smart decisions. You don’t need a finance degree. You need a few core skills and the habit of using them.
1.1 What Does Financial Literacy Actually Mean?
Think of it as three separate skills that work together:
| Skill | What it means | Example |
| Earning | Bringing money in | Salary, freelance work, a side business |
| Managing | Deciding where money goes | Budgeting, saving, paying bills on time |
| Building wealth | Making money grow | Investing, retirement accounts, income-producing assets |
Plenty of people earn well and manage poorly. Others earn modestly, manage brilliantly and end up ahead. Your income opens the door. Your money decisions decide what happens once you walk through.
1.2 Why Is Financial Literacy Important in Everyday Life?
Every money choice you make, from a $6 latte to a $30,000 car loan, runs through what you know. Strong skills help you:
- Spend with purpose. You see what a purchase really costs.
- Avoid unnecessary debt. You spot expensive borrowing before it traps you.
- Save and invest consistently. You treat both as habits, not leftovers.
- Handle emergencies. A blown tire stays an annoyance instead of a crisis.
- Work toward financial independence. You build options, one decision at a time.
1.3 What Are the Five Essential Components of Financial Literacy?
- Earning and managing income. Know what comes in and what you keep.
- Budgeting and managing expenses. Tell your money where to go.
- Saving and emergency funds. Build a cushion before you need one.
- Borrowing and credit. Use debt as a tool, not a crutch.
- Investing and planning. Put your money to work for your future self.
Pro tip: If you learn best from books, Financial Literacy Essentials For Dummies by Eric Tyson covers all five areas in beginner-friendly language.
1.4 Who Needs Financial Literacy?
Anyone with a paycheck, including:
- College students and recent graduates facing student loans
- Young professionals landing a first real salary
- Working adults juggling household bills
- Parents planning for childcare and college costs
- Anyone within sight of retirement
Whichever group fits you, the starting point looks the same: you need to see where your money goes today. That means income and expenses.
2. How Can You Build Essential Personal Finance Skills?
These personal finance basics hold up everything else in this guide. Get them right and the later sections get much easier.
2.1 How Do You Understand Your Income and Expenses?
Income arrives in four common forms:
- Salary or hourly wages
- Freelance earnings
- Business income
- Investment income, such as dividends and interest
Next, learn the difference between gross and net. Gross income is your pay before taxes and deductions. Net income is your take-home pay. Budget with net income, because that’s the money you can actually spend. (A $70,000 salary does not drop $5,833 into your account every month. I wish it did.)
Now sort your expenses:
| Type | Definition | Examples |
| Fixed | Same amount every month | Rent, car payment, insurance |
| Variable | Changes month to month | Groceries, utilities, gas |
| Discretionary | Optional | Dining out, streaming, hobbies |
Needs keep you housed, fed, employed and insured. Wants make life fun. Both belong in your plan. Budgets break when people mislabel one as the other. Your fifth streaming service is a want.
2.2 How Do You Calculate Your Net Worth?
Net worth shows where you stand today.
Net Worth = Total Assets – Total Liabilities
Assets are things you own that carry value: cash, savings, retirement accounts, investments, a car, a home. Liabilities are what you owe: student loans, credit card balances, car loans, mortgages.
| Assets | Amount | Liabilities | Amount |
| Checking | $3,000 | Student loan | $15,000 |
| Savings | $4,000 | Credit card | $3,000 |
| Retirement account | $12,000 | Car loan | $6,000 |
| Car | $9,000 | ||
| Total | $28,000 | Total | $24,000 |
Net worth here: $28,000 – $24,000 = $4,000.
A negative number is common early in adult life, especially with student loans. Don’t panic. Treat it as a starting line. Recalculate every three months and watch the direction of travel, not any single number.
2.3 How Can You Develop Better Money Management Habits?
Habits beat willpower every time. Start with these six:
- Track every dollar for 30 days.
- Set realistic financial goals.
- Review your expenses monthly.
- Wait 48 hours before unplanned purchases.
- Send money to savings automatically.
- Make each money decision on purpose.
Good habits need a system to hold them. That system is a budget.
3. How Do You Create a Budget and Manage Your Money Effectively?
3.1 Why Is Budgeting the Foundation of Personal Finance?
A budget is a plan for your money, written before you spend it. It answers the “where did it all go?” question before you ask it.
Budgeting matters at every income level. Someone earning $40,000 and someone earning $140,000 both watch money vanish without a plan. A budget also builds financial discipline, because you set priorities once instead of renegotiating them every time you tap your card.
3.2 How Do You Create a Monthly Budget Step by Step?
Follow these six steps:
- Calculate your monthly take-home income. Use net pay, and average it if your income varies.
- List your fixed expenses. Rent, insurance, loan payments, subscriptions.
- Estimate variable and discretionary spending. Pull the last two or three months of bank statements.
- Assign money to savings and debt repayment first. Pay your future self before the fun money.
- Monitor spending through the month. Check in weekly.
- Review and adjust. Fix what didn’t work.
Pro tip: Your first budget will be wrong. Mine missed by almost $400 in month one. That’s normal. Adjust and keep going.
3.3 What Is the 50/30/20 Budgeting Rule?
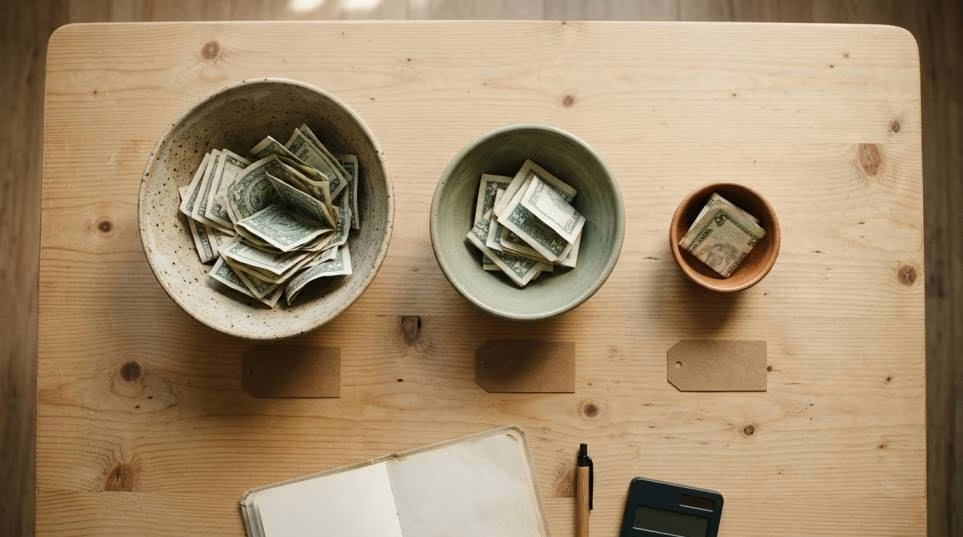
The 50/30/20 rule splits your take-home pay into three buckets:
- 50% for needs
- 30% for wants
- 20% for savings and debt repayment
Here’s how it looks on $5,000 of monthly take-home pay:
| Category | Percentage | Amount |
| Needs | 50% | $2,500 |
| Wants | 30% | $1,500 |
| Savings and debt repayment | 20% | $1,000 |
Treat it as a starting guideline, not a law. If you live in an expensive city and rent eats 45% of your pay, your split might look like 60/20/20. That still works. Adjust the percentages to fit your housing costs, income and goals.
3.4 What Are the Best Budgeting Methods for Beginners?
| Method | How it works | Advantage | Limitation |
| Zero-based | Assign every dollar a job until nothing is left unassigned | Total control | Takes more time |
| 50/30/20 | Three simple buckets | Easy to start | Too broad for tight budgets |
| Envelope | Fixed spending limit per category | Stops overspending | Awkward for online purchases |
| Pay-yourself-first | Save first, spend the rest | Builds savings automatically | Tracks spending loosely |
| Paycheck | Plan each paycheck on its own | Fits irregular bill dates | Needs frequent attention |
Pick one and run it for three months before you judge it. If you like the paycheck method, Budget by Paycheck from The Budget Mom is a practical workbook (about $48 at last check).
3.5 How Can You Track Your Monthly Expenses?
Choose the tool you will actually open:
- Spreadsheets. Free and flexible. Perfect if you like control.
- Budgeting apps. YNAB (about $109 a year, with a trial period at last check) gives every dollar a job. Monarch Money (about $99.99 a year) shows budgets, debt, investments and net worth in one dashboard. Prices change, so confirm before you subscribe.
- Paper planners. The Erin Condren Mantra A5 Budget Planner suits people who think better with a pen.
- Bank transactions. Scan them weekly.
- Recurring subscriptions. Audit them every quarter. Everyone finds at least one they forgot.
You can start free. A spreadsheet beats an unused app every day.
3.6 What Are the Most Common Budgeting Mistakes to Avoid?
- Underestimating expenses. Use real statements, not guesses.
- Forgetting irregular costs. Car repairs, gifts and annual fees hit hard. Divide them by 12 and save monthly.
- Setting unrealistic limits. A $50 grocery budget for a family of four sets you up to quit.
- Ignoring small purchases. Three $7 coffees a week adds up to over $1,000 a year.
- Skipping the review. A budget you never revisit is just a wish.
Once your budget runs smoothly, you can build the cushion that protects it.
4. How Can You Save Money and Build an Emergency Fund?
4.1 Why Is Saving Money Important for Financial Security?
Savings give you choices. With accessible cash, you can:
- Cover surprise expenses without a credit card
- Handle a job gap without panic
- Fund purchases and goals on your terms
Without savings, every surprise turns into debt. With savings, a surprise becomes a bill you pay and forget.
4.2 How Much of Your Income Should You Save Every Month?
A common guideline is 20% of your take-home pay, the savings slice of the 50/30/20 rule. If that number scares you, start smaller. Saving $25 a week adds up to $1,300 a year. Consistency beats size.
Then raise your rate over time. Each time your income grows, bump your savings percentage by 1% or more. You will barely feel it.
4.3 What Is an Emergency Fund and How Much Should You Have?
An emergency fund is money set aside only for true emergencies: job loss, medical bills, urgent car or home repairs. It differs from regular savings because it has one job. A vacation or a flash sale does not qualify.
A common target is three to six months of essential living expenses. It’s a guideline, not a requirement for everyone. Singles with stable jobs may feel fine near three months. Parents or freelancers often aim higher.
| Monthly essential expenses | 3 months | 6 months |
| $2,500 | $7,500 | $15,000 |
| $3,000 | $9,000 | $18,000 |
| $4,000 | $12,000 | $24,000 |
Those numbers can feel huge. Start with a $1,000 starter fund, then build from there.
Keep the money in a separate, easy-to-reach account, ideally a high-yield savings account (more on that below). Use it only for emergencies, then refill it as soon as you can.
4.4 What Are the Best Ways to Save Money Consistently?
- Automate transfers on payday.
- Cancel unused subscriptions.
- Cook more meals at home.
- Compare prices before big purchases.
- Set savings targets with names, like “Car Repair Fund.”
- Avoid lifestyle inflation, which means spending more every time you earn more.
Pro tip: Automation wins. If saving needs a decision each month, it will lose to a bad week.
4.5 What Is the Difference Between a Regular Savings Account and a High-Yield Savings Account?
Both accounts pay interest. The rate of return is quoted as APY (Annual Percentage Yield), the amount you earn in a year including compounding.
| Feature | Regular savings | High-yield savings |
| Interest rate | Usually low | Usually much higher |
| Typical provider | Traditional banks | Often online banks |
| Access | Easy | Easy |
| Best for | Convenience | Emergency fund and short-term goals |
Rates change with the economy, so compare current APYs before you open an account. Also confirm FDIC coverage. FDIC insurance protects deposits up to $250,000 per depositor, per insured bank, for each ownership category. You can check any bank on the FDIC website.
4.6 How Can You Build a Savings Habit That Lasts?
- Set a clear goal with a dollar amount and a date.
- Pay yourself first.
- Automate your contributions.
- Check progress monthly.
- Celebrate milestones, such as your first $1,000.
Savings protect you from the unexpected. Debt does the opposite, so you need to understand it next.
5. How Do Credit Scores Work and How Can You Manage Debt?
5.1 What Is a Credit Score and Why Does It Matter?
A credit score is a three-digit number, usually between 300 and 850, that estimates how reliably you repay borrowed money. Lenders check it when you apply for credit cards, auto loans, mortgages and sometimes apartments.
The two major scoring models are FICO and VantageScore. A higher score usually means better approval odds and lower interest rates. On a big loan, a better rate saves you thousands of dollars.
5.2 What Factors Affect Your Credit Score?
FICO publishes the approximate weight of each factor:
| Factor | Approximate weight | What it means |
| Payment history | 35% | Do you pay on time? |
| Amounts owed (utilization) | 30% | How much of your available credit you use |
| Length of credit history | 15% | How long your accounts have existed |
| New credit | 10% | Recent applications |
| Credit mix | 10% | Different types of accounts |
Different scoring models weigh these differently, so your scores will vary a bit between sources. Payment history and utilization drive the biggest changes.
5.3 How Can You Build or Improve Your Credit Score?
- Pay every bill on time. Set up autopay for at least the minimum.
- Keep balances low. Aim to use under 30% of each card’s limit. Lower is better.
- Apply for credit only when you need it.
- Check your credit reports. You can get free reports at AnnualCreditReport.com.
- Dispute errors. The CFPB explains how to dispute inaccurate information.
- Keep old accounts open when they carry no annual fee.
Pro tip: Your score moves slowly in your favor and quickly against you. Protect your payment history first.
5.4 What Is the Difference Between Good Debt and Bad Debt?
Good debt helps you build long-term value at a manageable cost. Bad debt carries high interest and funds things that lose value. The line blurs sometimes, so affordability matters most.
| Debt type | Usually viewed as | Why |
| Mortgage | Productive | Builds equity in a home |
| Student loans | Depends | Can raise earning power, but balances can overwhelm you |
| Personal loans | Depends | Fine for consolidating high-rate debt, risky for spending |
| Credit cards | Expensive | Interest rates are often very high |
Ask one question before borrowing: Can I repay this comfortably, and does it improve my future?
5.5 What Are the Best Strategies for Paying Off Debt?
Two methods dominate. Both work.
Debt Snowball
- Pay minimums on every debt.
- Throw all extra money at the smallest balance.
- When it’s gone, roll that payment into the next smallest debt.
Debt Avalanche
- Pay minimums on every debt.
- Put extra money on the highest interest rate.
- Repeat until you clear every debt.
Here’s an example with three debts:
| Debt | Balance | Rate | Snowball order | Avalanche order |
| Store card | $600 | 22% | 1st | 2nd |
| Credit card | $4,000 | 27% | 2nd | 1st |
| Car loan | $6,000 | 7% | 3rd | 3rd |
The snowball gives you quick wins that keep you motivated. The avalanche saves more interest. The best method is the one you will stick with. For a motivating, step-by-step approach, check out Get Good with Money by Tiffany Aliche.
5.6 How Can You Avoid Credit Card Debt?
- Spend within your limits, using cash flow, not credit limits, as your guide.
- Pay your full statement balance every month.
- Never settle for the minimum payment when you can pay more.
- Read your card’s interest rate (APR) and learn how it adds up.
- Never use credit to fund a lifestyle your income can’t support.
Debt works against you through interest. Compound interest, the same force, can also work for you. Let’s flip it.
6. How Does Compound Interest Help You Save and Build Wealth?
6.1 What Is Compound Interest?
Compound interest means you earn interest on your original money plus the interest it already earned. Your earnings start earning too.
Simple interest only pays on your original amount. Take $1,000 at 5%:
- Simple interest: $50 every year
- Compound interest: $50 in year one, $52.50 in year two, and the gap keeps growing
6.2 How Does Compound Interest Work?
Let’s use a hypothetical example: $5,000 invested at a 7% annual return, compounded yearly, with no additional contributions.
| Years | Approximate value |
| 10 | $9,836 |
| 20 | $19,348 |
| 30 | $38,061 |
Your $5,000 nearly quadruples by year 30, and you never add another dollar. The 7% return is a hypothetical assumption, not a promise. Real returns rise and fall, and investments can lose value.
6.3 Why Does Starting Early Matter When Building Wealth?
Time is the secret ingredient. Compare two people who each invest $5,000 once and never add more:
| Person | Starts at | Years invested (to age 65) | Hypothetical value at 7% |
| Ava | 25 | 40 | about $74,872 |
| Ben | 35 | 30 | about $38,061 |
Ben waited 10 years and gave up about $36,800. Same money. Same return. Different start date.
Compounding rewards patience, consistent contributions and discipline. It does not reward panic or perfect timing. The The Psychology of Money by Morgan Housel explains the mindset behind this beautifully.
6.4 How Can You Use Compound Interest to Your Advantage?
- Start early, even with small amounts.
- Reinvest eligible earnings such as dividends.
- Contribute consistently.
- Avoid unnecessary withdrawals.
- Watch fees and risks. A 1% annual fee eats a big chunk of long-term growth.
Ready to put your money to work? Let’s talk investing.
7. How Can Beginners Start Investing and Grow Their Money?
7.1 What Is Investing and Why Is It Important?
Investing means buying assets, such as stocks or funds, that may grow in value over time. Inflation shrinks the buying power of cash, so long-term goals usually need more than a savings account.
| Saving | Investing | |
| Goal | Safety and short-term needs | Long-term growth |
| Risk | Low | Higher, and you can lose money |
| Time horizon | Under 3 to 5 years | 5 years or more |
| Access | Immediate | May take time, and prices can drop when you sell |
Your investments should match your goals, timeline and comfort with risk.
7.2 How Much Money Do You Need to Start Investing?
Less than you think. Many platforms have low or no minimums, and fractional shares let you buy a slice of a stock for a few dollars.
But build the foundation first:
- Pay down high-interest debt.
- Build your emergency fund.
- Then invest.
Investing money you might need next month is a recipe for stress.
7.3 What Are the Main Types of Investments Beginners Should Understand?
| Investment | What it is | Main risk |
| Stocks | Ownership shares in a company | Prices swing, sometimes sharply |
| Bonds | Loans you make to governments or companies | Rising rates can lower prices; issuers can default |
| Mutual funds | Pooled money in many investments | Fees and market risk |
| ETFs | Funds that trade like stocks | Market risk; fees vary |
| Money market funds | Short-term, low-risk funds | Low returns; not FDIC insured |
| REITs | Companies that own real estate | Property market and interest-rate swings |
| Retirement accounts | Accounts (401(k), IRA) that hold investments | Depends on what you hold inside |
7.4 How Can You Start Investing in the Stock Market?
The stock market is where investors buy and sell shares of companies. When you own a share, you own a tiny piece of the business.
To begin:
- Open a brokerage account (or use your retirement account).
- Fund it.
- Pick your investments. Many beginners choose broad index funds or ETFs.
- Place your order. A market order buys at the current price right away. A limit order sets the price you’re willing to pay.
- Hold for the long term.
Pro tip: The Simple Path to Wealth by JL Collins offers a clear, beginner-friendly case for low-cost index investing. For free, unbiased basics, visit Investor.gov, the SEC’s investor education site.
7.5 What Is Investment Diversification and Why Does It Matter?
Diversification means spreading your money across many investments so one bad performer can’t sink you. Putting everything in one stock is like betting your whole paycheck on one horse.
Asset allocation is how you divide money among categories. Stocks tend to offer more growth and more swings. Bonds tend to offer more stability and less growth. Your mix depends on your age, goals and nerves.
7.6 What Are the Common Investment Mistakes Beginners Should Avoid?
- Buying what you don’t understand.
- Chasing trends. Last month’s hot tip is usually old news.
- Panic selling when markets drop.
- Ignoring fees.
- Investing money you need soon.
- Expecting guaranteed returns. No honest investment offers them.
Now zoom out. Investing works best when it serves a bigger plan.
8. How Do You Set Financial Goals and Plan for the Future?
8.1 What Are Short-Term, Medium-Term and Long-Term Financial Goals?
| Timeframe | Examples |
| Short-term (under 1 year) | Build a starter emergency fund, pay off a small debt |
| Medium-term (1 to 5 years) | Buy a car, fund education, save for a home down payment |
| Long-term (5+ years) | Retirement, financial independence, wealth creation |
8.2 How Do You Set SMART Financial Goals?
SMART goals are Specific, Measurable, Achievable, Relevant and Time-bound.
Weak goal: “Save more money.”
SMART goal: “Save $6,000 for my emergency fund in 12 months by transferring $500 on every payday of the month.”
Run the math: $6,000 divided by 12 equals $500 a month. If that’s too high, extend the timeline. A realistic goal beats an impressive one you abandon.
8.3 How Can You Start Planning for Retirement?
Start early, because compounding needs time.
- 401(k): An employer-sponsored plan that pulls contributions from your paycheck.
- Employer match: If your employer matches contributions, contribute enough to get the full match. It’s free money.
- IRA: An individual retirement account you open yourself.
| Account | Tax treatment (general) |
| Traditional 401(k) / IRA | You may deduct contributions now and pay tax when you withdraw |
| Roth 401(k) / Roth IRA | You contribute after-tax money and may withdraw qualified earnings tax-free |
Contribution limits and eligibility rules change, so check the IRS website before you contribute. Contribute consistently and review your investments once or twice a year.
8.4 Why Should You Understand Taxes and Insurance?
Taxes: Your taxable income is what remains after eligible deductions. The US uses progressive federal income tax brackets, which means each slice of your income faces its own rate. Learn the basics at IRS.gov.
Insurance: It shields you from losses that would otherwise wreck your finances.
| Type | Protects against |
| Health | Medical bills |
| Auto | Accident costs and liability |
| Life | Loss of income for dependents |
| Homeowners or renters | Property damage and theft |
Tax and insurance needs vary by situation. Treat this guide as education, and talk to a qualified tax professional or licensed insurance agent about your own case.
8.5 How Can You Calculate and Grow Your Net Worth Over Time?
Return to the formula from Section 2.2: total assets minus total liabilities. Recalculate quarterly. To grow it, build assets (savings, investments, retirement accounts) and trim unnecessary liabilities (high-interest debt).
Monarch Money can chart your net worth automatically if you prefer a dashboard.
Plans are only as good as the habits behind them. So let’s build those.
9. How Can You Build Healthy Financial Habits and Achieve Financial Independence?
9.1 What Financial Habits Should Everyone Develop?
- Live within your means.
- Save consistently.
- Spend intentionally.
- Avoid unnecessary debt.
- Invest based on long-term goals.
- Review your finances regularly. Block 30 minutes on your calendar monthly.
9.2 How Can You Avoid Lifestyle Inflation?
Lifestyle inflation happens when your spending rises every time your income does. A raise arrives, a nicer apartment follows, and your savings stay frozen.
Fight it this way:
- Split your raises. Save at least half of every pay increase before you adjust your lifestyle. I started doing this years ago and never looked back.
- Resist automatic upgrades.
- Raise your savings rate whenever income rises.
- Rank goals above status. Your neighbor’s car doesn’t pay your mortgage.
9.3 How Can You Develop Multiple Sources of Income?
One paycheck is a single point of failure. Consider adding:
- Career growth. Skills, certifications and promotions.
- Freelancing or consulting.
- A legitimate side business.
- Dividend and interest income.
- Income-producing assets. Investments or property that pay you over time.
Start with one extra stream and make it work before adding another. Beware of anything promising fast, effortless money.
9.4 What Is Financial Independence and How Can You Work Towards It?
Financial independence means your investments and passive income cover your living expenses, so work becomes a choice. It does not mean quitting your job tomorrow.
The path is simple, though not easy:
- Earn steadily.
- Keep expenses below income.
- Save a healthy share.
- Invest it consistently.
- Build resilience with emergency savings and insurance.
Nobody can promise a timeline. Consistency beats shortcuts. For a mindset shift, Your Money or Your Life by Vicki Robin and Joe Dominguez and I Will Teach You to Be Rich by Ramit Sethi both make great reads.
9.5 What Financial Mistakes Should You Avoid in Your 20s, 30s, 40s and 50s?
| Decade | Common mistakes |
| 20s | Spending without a plan, ignoring emergency savings |
| 30s | Taking on excessive debt, delaying retirement contributions |
| 40s | Underinsuring, letting lifestyle inflation grow |
| 50s | Neglecting retirement catch-up planning, investing on hype |
Whatever your age, the fix starts with the same step: take one action this week.
10. Frequently Asked Questions About Financial Literacy
10.1 What Is Financial Literacy and Why Is It Important?
It’s the ability to understand and manage money. It matters because it helps you spend wisely, avoid debt, handle emergencies and build wealth.
10.2 What Are the Five Basics of Financial Literacy?
Earning, budgeting, saving, borrowing and investing. Master these and you cover most everyday money decisions.
10.3 How Can Beginners Become Financially Literate?
Track your spending, build a budget, read one trusted book and use free tools like the CFPB toolkit, FDIC Money Smart and MyMoney.gov. Learn one topic at a time.
10.4 What Are the Four Main Principles of Personal Finance?
Budget, save, borrow responsibly and invest. Some lists add protect (insurance), but these four form the core.
10.5 How Do I Create a Budget and Manage My Money Effectively?
Calculate your take-home pay, list expenses, assign savings first, track spending and adjust monthly. Start with the steps in Section 3.2.
10.6 How Much of My Income Should I Save Each Month?
A common target is 20% of take-home pay. If that’s too much now, start with whatever you can and raise it gradually.
10.7 What Is an Emergency Fund and How Much Should I Have?
It’s cash reserved for true emergencies. Aim for three to six months of essential expenses, and start with $1,000 if you’re just beginning.
10.8 What Is the Difference Between Saving and Investing?
Saving protects money you need soon. Investing grows money for long-term goals but carries risk, including the chance of loss.
10.9 How Does Compound Interest Help Build Wealth?
Your earnings generate their own earnings. In our example, $5,000 at a hypothetical 7% grows to about $19,348 in 20 years.
10.10 How Can I Improve My Credit Score?
Pay on time, keep balances low, avoid needless applications and check your reports for errors.
10.11 What Is the Difference Between Good Debt and Bad Debt?
Good debt builds long-term value at a manageable cost. Bad debt carries high interest and funds things that lose value. Affordability decides.
10.12 How Can I Pay Off Debt Faster?
Use the snowball method (smallest balance first) for motivation or the avalanche method (highest rate first) to save interest. Add extra dollars to either.
10.13 How Much Money Do I Need to Start Investing?
Often just a few dollars through fractional shares. First clear high-interest debt and build an emergency fund.
10.14 What Should I Invest in as a Beginner?
Many beginners start with diversified, low-cost index funds or ETFs, often inside a retirement account. Learn the risks first, and no investment guarantees returns.
10.15 How Do I Calculate My Net Worth?
Add up your assets, add up your liabilities and subtract. With $28,000 in assets and $24,000 in liabilities, your net worth is $4,000.
10.16 How Can I Achieve Financial Independence?
Earn consistently, spend less than you make, save a healthy share and invest it for years. Expect it to take time.
Conclusion: How Can You Take Control of Your Financial Future?
Financial literacy isn’t reserved for the wealthy, the credentialed or the lucky. You can learn it, and you just read the roadmap.
Use this checklist:
- Know your income and expenses.
- Build a budget you can keep.
- Fund an emergency cushion.
- Save consistently and manage debt.
- Understand your credit score.
- Let compound interest work for you.
- Invest according to your goals and risk tolerance.
- Build habits that last.
- Review your plan regularly.
Financial freedom doesn’t happen overnight. It begins when you understand your money and make better decisions, one step at a time. So pick ONE habit today. Open a savings account, set up autopay or calculate your net worth. Then build from there, and your future self will thank you.
Which money skill do you most want to improve? Tell me in the comments, and explore more personal finance guides on MavenSynergy.com
This article offers educational information, not personalized financial, tax, investment or legal advice. Verify current figures and rules with official sources before you act.