15 Things to Do When You’re Struggling Financially (and How to Get Back on Track)
Your paycheck lands on Friday. By Monday, rent and a surprise car repair have swallowed it whole. If that sounds familiar, take a breath. You may be wondering what to do when you’re struggling financially, so let me say this first: you can turn this around. Plenty of Americans started right where you stand, and they climbed out one small step at a time. Every bill you tackle and every dollar you save moves you closer to the life you want.
Money trouble hits anyone, whatever your age or paycheck size. Inflation pushes prices up. A layoff cuts your income overnight. Low wages stretch thin, credit card balances grow, and impulse spending adds fuel. Often several of these land at once, and that is when the stress feels unbearable.
Here is the good news: you can recover, even with little income and almost no savings. In this guide, I give you 15 practical steps, from checking where your money goes to finding assistance and earning extra cash. Each step helps you get your finances back on track and get back on your feet financially. You do not need all 15 today. Pick one and start TODAY.
1. How Can You Assess Your Current Financial Situation?
You cannot fix a number you refuse to look at. I know that stings, but looking is the fastest way to calm your nerves. Fear grows in the dark. A page full of real numbers shrinks it.
Start by building a simple financial snapshot. Grab a notebook, a spreadsheet or the notes app on your phone, and write down:
- Your total monthly income after taxes, including side income and benefits
- Fixed expenses, like rent, car payments and insurance
- Variable expenses, like groceries, gas and takeout
- Every debt, with its balance, interest rate and minimum payment
- Your savings and any bills already past due
Pull your last two or three months of bank and card statements to fill the gaps. Your memory will fudge the details. Your statements will not.
Now do the math: income minus expenses. A negative number means you spend more than you earn, and now you know the size of the hole. Next, circle your biggest cost. For many Americans it is housing. Sometimes a pile of forgotten subscriptions or a daily delivery habit does the real damage.
Pro Tip: Finish this in one sitting and set a timer for 60 minutes. A deadline keeps you from spiraling.
Practical action: Create your one page snapshot today. Income, expenses, debts, savings and overdue bills.
2. How Can You Create a Realistic Budget When You’re Broke?
Budgeting matters MORE when money is tight, because every dollar has a job to do. A budget does not take your freedom away. It tells you where your money goes before it disappears.
Start with a bare bones budget. List only what keeps you housed, fed, healthy and employed. Everything else waits. Then pick the method that fits your life:
| Method | How it works | Best for |
| Zero based budget | Income minus expenses equals zero. Every dollar gets a job. | Tight incomes with little room for error |
| 50/30/20 rule | 50% needs, 30% wants, 20% savings and debt | Steadier incomes with some breathing room |
| Paycheck based plan | You assign each paycheck to the bills due before the next one | Weekly or biweekly pay |
Here is a quick example of the zero based method. Say you bring home $2,000 this month. Rent, food, utilities and transport add up to $1,800, and a debt minimum takes $150. That leaves $50, and you give it a job, such as your first emergency savings deposit. When the last dollar has a name, nothing leaks.
Be honest about the 50/30/20 rule. If rent alone eats 60% of your pay, it will not fit yet. Use it as a target to grow toward, not a reason to feel like you failed.
For the paycheck based plan, write the bills due before your next payday under each check. Whatever remains goes to food and gas. It feels almost too simple, and that is why it works.
Pro Tip: Build your budget in a spreadsheet, a free budgeting app or a plain notebook. The best tool is the one you open every week.
Practical action: Build a one month budget today and tape it somewhere you see daily.
3. How Should You Prioritize Bills When You Can’t Afford Everything?
Not every bill is equal. Miss a streaming payment and you lose a show. Miss rent and you could lose your home.
Pay in this order: housing, utilities, food, essential transportation and necessary healthcare. Then cover minimum payments on debts. Last come the extras.
Let me show you with a real example. Say you take home $2,800 a month:
| Priority | Expense | Monthly cost |
| 1 | Rent | $1,350 |
| 1 | Utilities | $210 |
| 1 | Groceries | $420 |
| 1 | Gas and car insurance | $360 |
| 1 | Medical costs and prescriptions | $80 |
| 1 | Phone | $70 |
| 2 | Credit card minimum | $140 |
| 2 | Personal loan minimum | $120 |
| 3 | Streaming and subscriptions | $45 |
| Total | $2,795 |
You have $5 left. That is tight, but it works on paper. If something breaks, priority 3 goes first.
Rent deserves special attention. If you see a shortfall coming, talk to your landlord early, because most would rather work out a plan than start an eviction. Call 211 as well, since many areas run emergency rental help.
What if you cannot pay even the minimums? Call the lender BEFORE you miss the date. Ask about hardship plans, a lower payment or a due date change. Most lenders prefer a smaller payment over none. Then write every due date on a calendar so no late fee sneaks up on you.
Pro Tip: Pay the bills with the harshest consequences first. Eviction, utility shutoffs and car repossession hurt far more than a late credit card payment.
Practical action: Create a bill priority list and a payment calendar this week.
4. What Expenses Should You Cut When Money Is Tight?
Cutting expenses does not mean living on rice forever. It means finding the money you waste without noticing.
Start with an expense audit. Scan your last month of statements and highlight every charge you did not need. People tend to find at least one subscription they forgot they had. Cancel it right now, while you remember.
| Category | Quick moves |
| Groceries | Plan meals, shop with a list, buy store brands and cook at home |
| Transportation | Carpool, combine errands, shop for cheaper car insurance |
| Utilities | Lower the thermostat, switch to LED bulbs, unplug idle electronics |
| Subscriptions | Cancel, pause or share a plan with family |
| Dining out | Cut it to special occasions until you recover |
Now sort what remains into two piles. One pile holds temporary sacrifices, like takeout or the gym membership you barely use. The other holds things that truly improve your life, like a cheap hobby that keeps you sane. Cut the first pile hard. Trim the second one gently. You need joy to stay on the plan.
Pro Tip: Pause a subscription instead of canceling it if you plan to return. Many services let you do this, and you keep your account.
Practical action: Pick five expenses to eliminate, reduce or pause this month.
5. How Can You Negotiate Bills and Reduce Your Monthly Payments?
Here is something most people never try: they ask. Companies hear hardship requests every day, and many have programs they never advertise.
Before you call, gather your account number, your payment history and the exact amount you can afford. Then say it plainly:
“I’m having trouble keeping up with my payments. What hardship options or lower cost plans do you offer?”
Use that line with:
- Phone and internet providers, who may offer cheaper plans or loyalty discounts
- Insurance companies, who can run new quotes or adjust your coverage
- Utility companies, who often offer payment plans and hardship funds
- Lenders and landlords, who may agree to an extension or a revised due date
- Federal student loan servicers, who can talk through income based repayment options
If the first rep says no, stay polite and ask for a supervisor or the retention team. Ask about late fee waivers too. Write down the date, the name of the person and what they promised. Then ask for the agreement in writing.
Pro Tip: Call early in the day, when you have time and patience to spare. Rushed calls lead to weak deals.
Practical action: Contact at least two providers this week and ask about discounts, hardship arrangements or lower cost plans.
6. How Can You Get Out of Debt When You’re Financially Struggling?
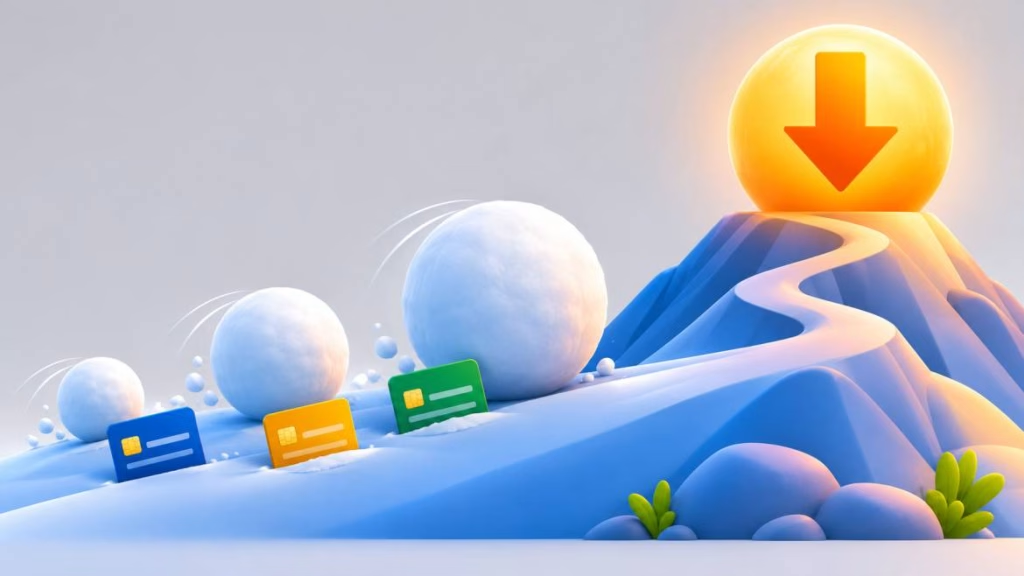
Ignoring debt does not make it disappear. It makes it bigger, with interest and late fees stacking on top.
Start by listing every debt with its balance, interest rate and minimum payment. Keep paying every minimum so you protect your credit and avoid penalties. Then throw any extra cash at ONE debt.
| Method | How it works | Why you might pick it |
| Debt snowball | Pay the smallest balance first, then roll that payment to the next | Quick wins keep you motivated |
| Debt avalanche | Pay the highest interest rate first | Saves the most money over time |
Both methods work. The best one is the one you stick with. If you need early victories to stay motivated, pick the snowball. If math excites you, pick the avalanche.
Credit card debt deserves a phone call too. Ask your card company about a hardship program, a lower rate or a temporary payment reduction. Some issuers will agree, especially when you call before you fall behind.
Stop adding new debt while you climb. Put the credit cards away and use cash or a debit card for daily spending. And if your debts feel too large to handle alone, a reputable nonprofit credit counselor can build a plan with you (more on that in step 15).
One warning: do NOT stop paying your debts indiscriminately. Skipping payments can wreck your credit and trigger collections or lawsuits. Always talk to the lender first.
Practical action: Write your debt repayment plan and mark the debts that need attention first.
7. How Can You Find Financial Assistance When You’re Struggling?
Asking for help does not mean you failed. These programs exist because life happens to everyone, and you have probably paid taxes that fund them.
Here are the main US resources to check:
- SNAP helps eligible households buy groceries.
- LIHEAP helps eligible households with heating and cooling bills.
- Unemployment insurance pays eligible workers who lose a job through no fault of their own. You apply through your state workforce agency.
- United Way 211 connects you with local help. Dial 211 or visit 211.org.
- Food banks and pantries offer free groceries, usually with few questions.
- Local nonprofits and churches sometimes offer rent or utility assistance.
Start with 211. One call can point you to food, housing, utility and medical help in your area. You can also check benefits.gov to see which federal programs you may qualify for.
Eligibility rules and benefits vary by state and by household, so confirm the details on official .gov sites or with your local office. Gather your ID, proof of income and a recent bill before you apply. It speeds things up.
Pro Tip: Apply for several programs at once. Waiting lists can be long, and one approval often makes another easier.
Practical action: Identify at least two assistance resources in your state or community and contact them this week.
8. How Can You Increase Your Income When You’re Struggling Financially?
Cutting expenses has a floor. You cannot cut below zero. At some point, you must earn more.
The fastest route often sits inside your current job. Ask your supervisor about overtime or extra shifts. If you have performed well, request more responsibility or a salary review, and bring examples of your results. Even a small raise adds up over a year.
If your job has hit a ceiling, look at better paying roles. Update your resume, tell friends and former coworkers you are searching and set a goal of two applications a week. Check job boards, but also your state workforce office, which often runs free job help.
You can also turn existing skills into cash. Can you cook, fix cars, organize closets, edit videos, write or teach? Someone will pay for that. Temporary, freelance and part time work can bridge a gap while you hunt for something better.
Be strategic with your search. Tell recruiters exactly what you want, apply to roles that match your skills, and follow up within a week. A quick, polite note often moves your resume to the top of the pile.
Think about this. If you earn an extra $300 a month, that adds $3,600 a year. Aim that money at your emergency fund or your highest interest debt, and watch your situation change.
Pro Tip: Ask for work you can start within days, not weeks. Speed matters when bills are due.
Practical action: Identify three realistic ways to increase your income and pick one to act on this week.
9. What Side Hustles Can You Start When You’re Broke?
The best side hustles cost little or nothing to start. If a “business opportunity” demands big upfront money, walk away.
Here are options that fit a tight budget:
- Freelancing and remote services, such as data entry or customer support
- Virtual assistance and administrative help for busy owners
- Online tutoring and teaching, if you know a subject well
- Delivery driving and local gigs, like grocery shopping or moving help
- Writing, graphic design and other digital services
- Selling digital products and templates, such as budget spreadsheets or planners
I love that last one, because you build it once and sell it many times. But it takes patience. Gigs like delivery pay faster, so match your pick to how soon you need cash.
Choose ONE hustle that fits your skills, your free hours and your wallet. Doing one well beats juggling five badly. Give it 30 days, track what you earn and keep going if it works.
Watch out for anything that asks you to pay a fee to get hired. Real employers pay you. They do not charge you.
Pro Tip: Treat side income as a bill payer. Send every dollar straight to your priority list, not to extra spending.
Practical action: Choose one side hustle and take the first step today, whether that means creating a profile or sending a pitch.
10. How Can Selling Unused Items Help Improve Your Financial Situation?
You may be sitting on hundreds of dollars without knowing it. Look in your closet, garage and storage bins.
Items that often sell well include electronics, furniture, clothing, tools, sports gear and kitchen appliances. Check each item and ask: have I used this in the last six months? If not, it is a candidate.
Use well known marketplaces, such as Facebook Marketplace, eBay, OfferUp or Poshmark, depending on what you sell. Search for the same item to see what others charge, then price a bit below the top listings so yours moves fast. Take clear photos in good light and write an honest description.
Protect yourself from scams:
- Meet buyers in a public place, in daylight
- Take cash or use the platform’s own payment system
- Never accept a check for more than the price and send back the difference
- Ignore buyers who ask you to click odd links or move the chat off the platform
Then decide where the money goes BEFORE it hits your account. Use it for an urgent bill, a debt or your emergency fund, not for a celebration dinner.
Pro Tip: List at least ten items in one weekend. More listings mean more chances for a quick sale.
Practical action: Identify five items you no longer need and list them for sale this week.
11. How Can You Save Money Even When You’re Broke?
You are probably asking, “How can I save when I can barely cover my bills?” Fair question. But saving a little builds a habit, and the habit matters more than the amount.
Start tiny. Five dollars a week is $260 a year. That is real money when you had none. Pick a number you will not miss and stick to it.
Try these moves:
- Set up an automatic transfer on payday, even if it is only $10
- Open a separate savings account so you do not spend the cash by accident
- Save every windfall, like a tax refund, a gift or a bonus
- Round up purchases and save the difference
- Move any money you free up by cutting expenses
Consistency beats size. A person who saves $10 every week for a year ends up ahead of a person who saves $200 once and quits.
But do not sacrifice the basics to save. Skipping a prescription or a meal to hit a target backfires fast. Cover your needs first, then save what remains.
Pro Tip: Name your savings account after a goal, like “Rent Safety Net.” A name keeps the purpose in front of you.
Practical action: Set a weekly or monthly savings target today, even if it starts at a few dollars.
12. How Can You Build an Emergency Fund on a Low Income?
An emergency fund is money you set aside for surprises, like a car repair, a medical bill or a sudden job loss. Without one, a single bad week can push you straight back into debt.
Start small. Your first goal could be $250 or one week of essential expenses. Then aim for one month of essentials. Once you reach that, work toward three to six months, which gives you real breathing room if you lose income.
How do you get there? Divide your goal into small weekly pieces and automate each one. Add windfalls, side hustle income and money from sold items. Every contribution counts.
Here is the math that makes it feel doable. Suppose your essentials cost $2,000 a month. One month of cover is $2,000, and saving $40 a week gets you there in a year. It is slow, but every deposit protects you more than the last.
Keep the money somewhere safe and easy to reach, like a high yield savings account at an FDIC insured bank. Skip risky investments and long locked accounts. You need this cash fast, without losing value.
Use it only for true emergencies. A sale on shoes is not an emergency. A broken water heater is. When you spend from the fund, rebuild it as soon as you can.
Pro Tip: Keep your emergency fund at a different bank than your checking account. A little distance stops casual dips.
Practical action: Calculate your essential monthly expenses and set your first emergency savings target.
13. How Can You Change Your Spending Habits and Avoid Future Financial Problems?
Sooner or later, every recovery comes back to habits. You can earn more, but if spending runs the show, you end up in the same place.
Start by spotting emotional spending. Do you shop when you feel stressed, bored or sad? Many of us do. Notice the trigger, and you take away its power.
Then sort every purchase into a need or a want. Needs keep you safe and working. Wants are nice but optional. You can still buy wants, once your needs and savings sit safe.
Here is how it looks in real life. You scroll your phone on a rough Tuesday and spot a $60 pair of shoes. Do need them. You want a win after a bad day. Put them in the cart, close the app and walk away. Odds are you forget them by dinner.
Try the 24 hour rule. When you want something that is not essential, wait a full day. Most urges fade by morning. If you still want it, add it to the budget.
More tools that help:
- Cash envelopes for categories like groceries and fun
- Digital spending limits through your bank app
- A weekly 15 minute review of every purchase
- Deleting saved card details from shopping apps
Pro Tip: Unsubscribe from store emails. You cannot buy what you never see.
Practical action: Pick ONE spending control habit and track your progress for 30 days.
14. How Can You Set Financial Goals and Get Your Finances Back on Track?
Vague wishes like “I want more money” go nowhere. Specific goals create a path. Aim for goals you can measure and finish.
Think in two time frames:
| Plan | What to include |
| 30 day plan | Finish your snapshot, build your budget, cancel waste, call two providers and start saving |
| 90 day plan | Reach a savings target, pay off your smallest debt, add income and build momentum |
Here is an example of a clear 90 day goal: “I will save $500, pay off my $300 store card and earn an extra $200 a month.” You can check each part. You know when you win.
Write each goal with a number and a date. “Save more” does not work. “Save $300 by January 31” does.
Track progress with simple indicators: your savings balance, your total debt, your monthly surplus and the number of bills paid on time. Update them every Sunday, and keep a chart on your fridge or phone.
Celebrate wins, but keep the celebration cheap. A walk in the park, a favorite home cooked meal or a movie night at home keeps morale high without hurting your budget.
Pro Tip: Share your goals with one person you trust. Accountability helps more than willpower alone.
Practical action: Set three measurable financial goals for the next 90 days and write them down.
15. How Can You Get Professional Financial Help and Protect Yourself From Scams?
Some situations need more than a budget. If debt collectors call daily, your bills keep growing or panic keeps you from acting, get professional help.
Start with a nonprofit credit counseling agency. Organizations that belong to the National Foundation for Credit Counseling (NFCC) offer budget help and debt management plans, often for a low fee or none. A good counselor reviews your whole situation and explains your options clearly, including the downsides.
Spot a legitimate counselor by checking that they:
- Operate as a nonprofit
- Explain fees up front, in writing
- Offer several solutions, not just one
- Never pressure you to sign right now
If you work with a counselor, bring your snapshot from step 1, your latest statements and a list of your debts. The more you share, the better the plan fits.
Now the scary part. Desperate times attract predators. Run from any company that promises guaranteed results, charges big fees before doing anything or tells you to stop talking to your creditors. Be careful with payday loans, car title loans and other predatory lenders. Their rates can bury you deeper.
Learn the scam signs. Real assistance programs never ask you to pay to apply. Check any offer on the Consumer Financial Protection Bureau site (consumerfinance.gov), and report fraud to the Federal Trade Commission at reportfraud.ftc.gov.
Pro Tip: I am not a licensed financial advisor, and this guide does not replace personal advice. For big decisions about debt or legal issues, talk with a qualified professional.
Practical action: Find one reputable counseling or consumer protection resource and save its contact details now.
Frequently Asked Questions About Struggling Financially
1. What should I do first when I’m struggling financially?
Take stock before you act. List your income, expenses, debts and urgent bills. A clear picture stops you from making rushed choices, like grabbing a high interest loan, that make things worse.
2. How do I get out of financial trouble when I have no money?
Cover essentials first: housing, utilities, food and transport. Then negotiate bills, apply for assistance and look for quick income, like selling items or picking up gig work. Small moves add up fast.
3. How can I survive financially when my income isn’t enough?
Mix four moves: a bare bones budget, lower expenses, assistance programs like SNAP or LIHEAP and a second income source. No single move solves it, but together they close the gap.
4. How do I manage money when I’m completely broke?
Use a bare bones budget that covers only essentials. Track every dollar, avoid new borrowing and pay for daily spending with cash. Every purchase should pass one test: do I need this right now?
5. What bills should I prioritize when I can’t afford everything?
Look at the consequences of missing each one. Put housing, utilities, food, necessary healthcare and the transport you need for work first. Credit cards and subscriptions come later.
6. How can I stop living paycheck to paycheck?
Control spending, build even a tiny savings habit, raise your income and grow an emergency fund. The goal is a one month gap between you and your next paycheck. It takes time, so go step by step.
7. How can I save money when I barely have enough to pay my bills?
Start with $5 or $10 and cover your essentials first. Automate the transfer and save windfalls. Small, steady deposits build the habit, and the habit grows with your income.
8. How do I get out of debt when I’m financially struggling?
Pay every minimum, then pick the snowball or avalanche method for extra cash. Talk to your lenders about hardship options and consider a nonprofit credit counselor if the load feels too heavy.
9. What government assistance programs are available to people struggling financially in the US?
SNAP helps with food, LIHEAP with energy bills and unemployment insurance replaces part of lost wages. Call 211 for local help. Rules vary by state, so confirm details with official offices.
10. How can I make extra money when I’m broke?
Choose low cost options: freelancing, tutoring, delivery or temporary work, plus selling things you do not use. Pick one, give it 30 days and send every dollar to your priority bills.
11. How much should I save for emergencies when I’m struggling financially?
Begin with a small goal, such as $250 or one week of essentials. Then build toward one month, and eventually three to six months of essential expenses.
12. How long does it take to recover financially?
It depends on your income, your debt, the cause of the hardship and how consistent you stay. Some people feel relief in a few months. Bigger debts can take years. Progress shows up sooner than full recovery.
Conclusion: How Can You Start Getting Your Finances Back on Track Today?
Your struggle does not set your future. Many people who now live stable lives once stood exactly where you stand.
If 15 steps feel like a mountain, shrink it. Three priorities cover the whole guide: take control of your spending, handle your urgent bills and grow your income. Everything else supports those.
You do NOT need to do all 15 steps at once. Choose two or three, start today and keep going. Consistency, realistic goals and a little discipline beat any dramatic overnight fix.
Getting back on your feet financially does not happen overnight, but every smart choice moves you closer to stability. Start with what you control today, improve a little each week and keep showing up. Your current situation does not have to decide your financial future.
Which of these 15 steps will you start today? Share your thoughts in the comments, and find more practical personal finance tips on www.MavenSynergycom.